
Nepal UK
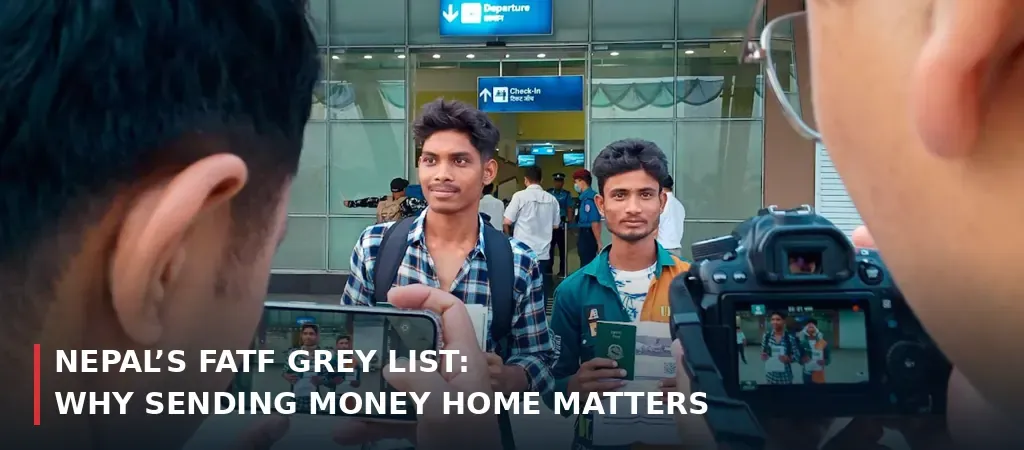
Nepal remains under increased monitoring by the global financial watchdog, with reform progress described as slow. For the diaspora, the issue is less about sanctions than about the cost and friction of moving money.
The Financial Action Task Force (FATF) kept Nepal on its "grey list" after its June 2026 plenary in Paris, according to ShareSansar, which lists six areas where Nepal must still act. Nepalese households and businesses overseas, who send remittances that underpin much of Nepal's economy, are among those with the most at stake.
What the record shows
Nepal was added to the list in February 2025. ShareSansar reports that the Asia/Pacific Group's January 2026 review found meaningful progress on only nine of 15 action-plan items, with six partly implemented. FATF's outstanding areas include risk understanding, supervision of banks, cooperatives, casinos, precious-metal dealers and real estate, action against illegal money-transfer ("hundi") operators, agency coordination, more money-laundering prosecutions, and asset tracing and confiscation.
Kantipur's reporting, summarised by the Kathmandu Post on 18 May 2026, said an Asia/Pacific Group delegation described progress as "disappointing" in a confidential briefing note and warned of possible blacklisting if reforms did not accelerate, with only 149 cases filed across agencies. These claims come from a leaked document and an unnamed-source report; the Post's piece is the only source seen for them and the government has not been shown to confirm them. Finance Minister Swarnim Wagle was reported as acknowledging that grey-listing has harmed Nepal's reputation and investment climate, and the government has repeatedly said it is committed to exit (ShareSansar, 20 May 2026).
Practical effect for the diaspora
Grey-listing is not a sanctions regime. ShareSansar notes it raises scrutiny of cross-border transactions and compliance costs for financial institutions, and that FATF itself cautioned against disrupting legitimate flows such as remittances. In practice, readers may encounter additional identity or source-of-funds questions. The sources reviewed did not quantify any change in remittance costs or delays, so no such figure is claimed here.
One clear takeaway: using regulated channels rather than informal "hundi" arrangements is the safest course, since informal transfer operators are specifically a target of the reforms.


